What Does Travel Insurance Cover in China in 2026?
China travel insurance is most useful for the bills a normal trip budget cannot absorb: emergency treatment, hospitalization, evacuation and serious trip interruption. This 2026 guide separates common benefits from exclusions, explains upfront hospital payments and direct billing, and gives you six essential documents to keep for a cleaner claim.
Most travel policies cover emergency illness, injury, hospitalization, evacuation and some trip disruption in China—but only under the policy's stated limits, exclusions and conditions. For 2026, use $100,000 emergency medical and $250,000 evacuation as screening benchmarks, then confirm mainland China is included on your exact dates.
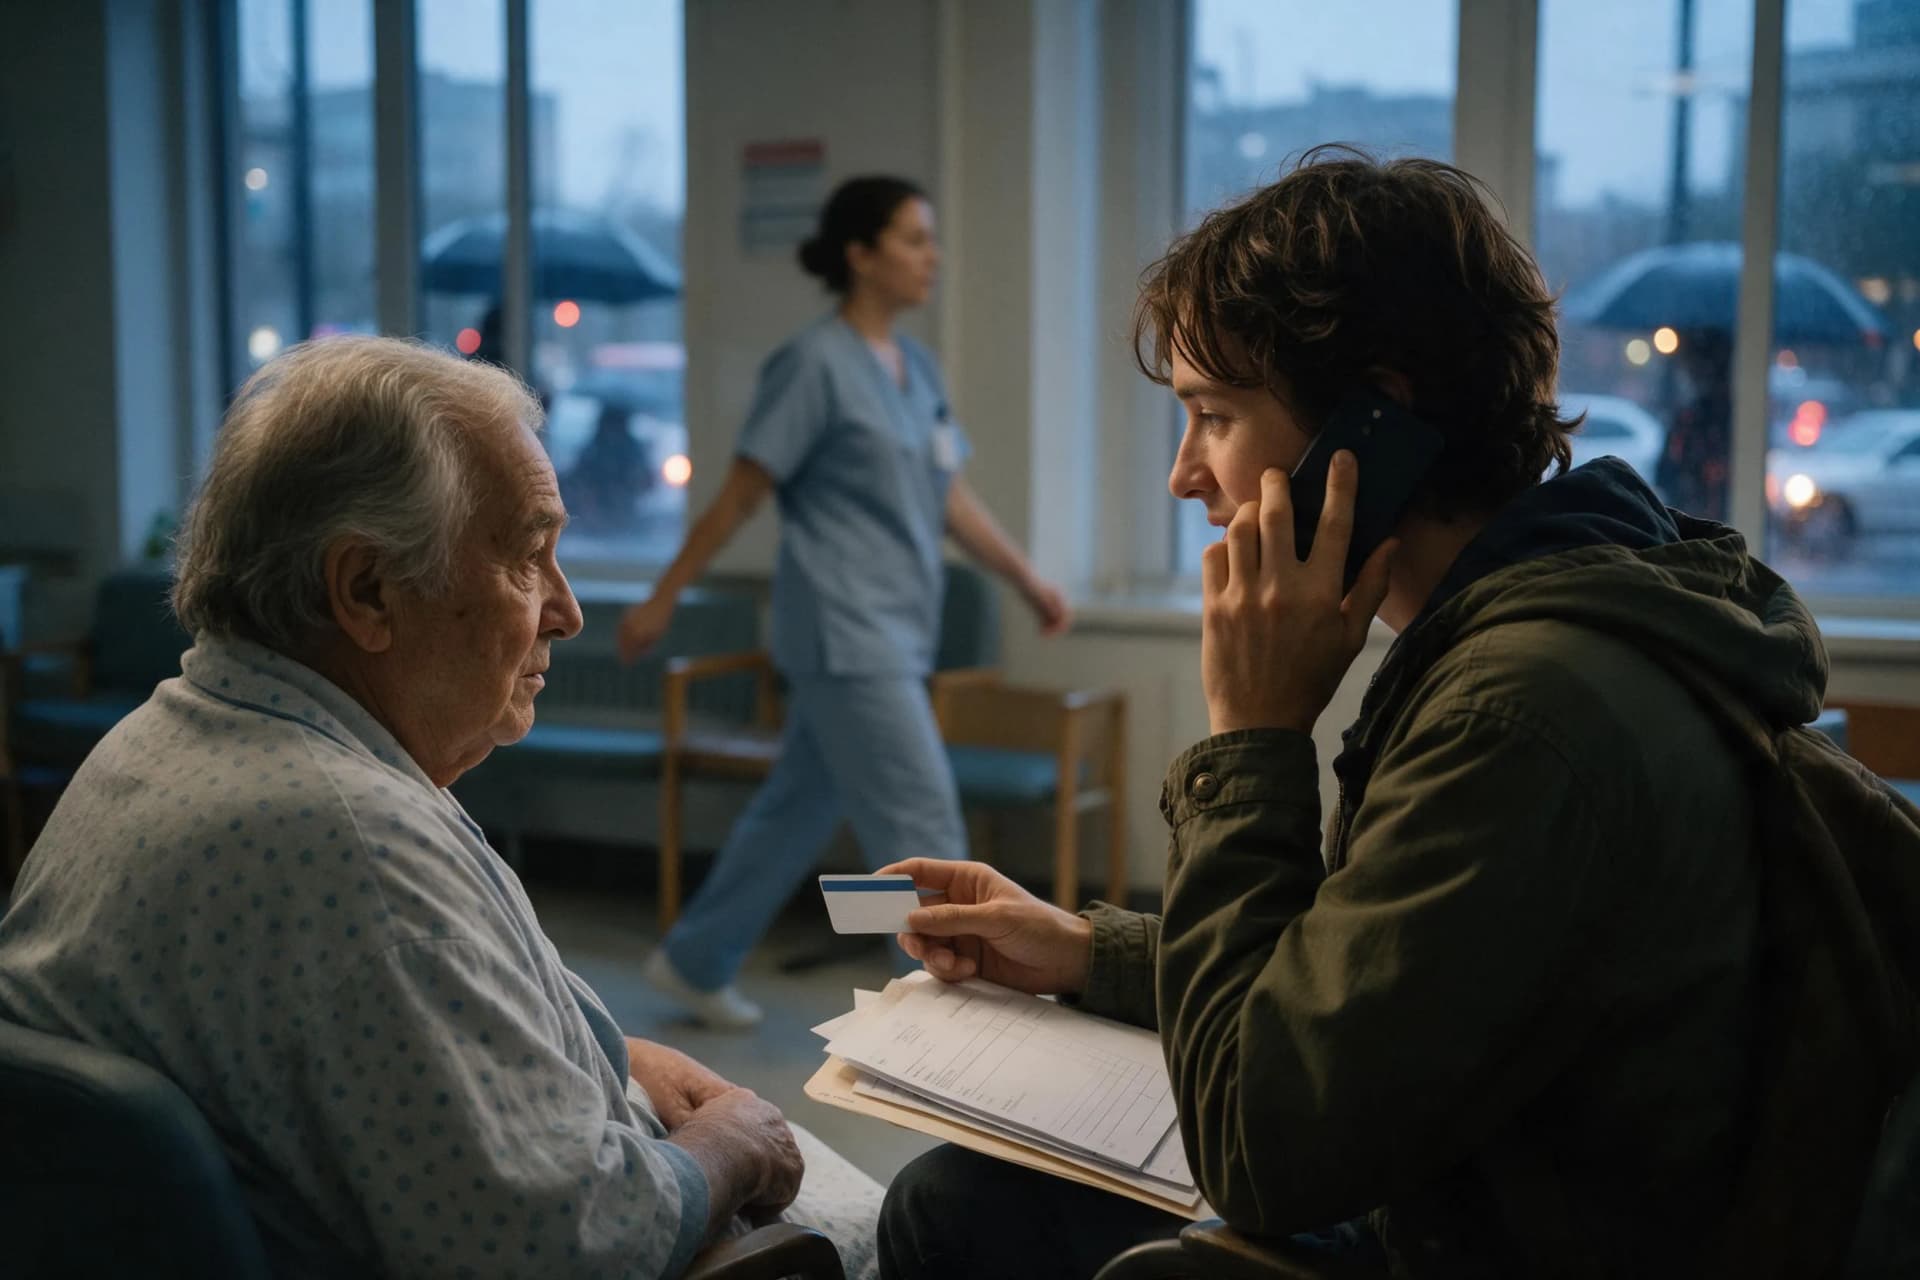
The hospital scene is rarely dramatic. More often, a traveler wakes in Chengdu with a fever, misses a train because of a twisted ankle, or discovers that a dental infection will not wait for the flight home. At that point the useful question is not “Did I buy travel insurance?” but “Which bills will this policy actually accept?” Read the certificate, not the shopping-page headline.
A travel-medical policy normally focuses on urgent, unforeseen problems. Check whether it pays for: • Hospital stays and emergency-room treatment • Doctor visits, tests, medicine and medically necessary surgery • Emergency dental treatment for sudden pain or injury • Medically necessary evacuation to the nearest suitable facility • Repatriation of remains or return home after treatment • A 24-hour assistance line that can coordinate care Each benefit has a cap, deductible and claim rule. A high overall limit does not mean every service receives that amount.
Separate cancellation and baggage benefits are optional on many travel-medical plans. Trip interruption may reimburse an unused hotel night or a replacement ticket when a covered illness, severe weather event or common-carrier failure ends a trip early. Baggage coverage may help after theft or airline delay. These protections are convenient, but they should not distract from the emergency medical and evacuation limits that matter most in China.
The exclusions decide whether the promise is real. Pay particular attention to pre-existing conditions, pregnancy, routine checkups, elective treatment, alcohol-related incidents, unattended belongings and adventure activities. Hiking and cycling may be covered while paragliding, scuba diving or a multi-day trek at altitude needs a specific extension. If you have asthma, heart disease or another ongoing condition, do not assume a policy will cover a flare-up merely because the emergency happens abroad.
China adds a practical payment wrinkle. Public hospitals may ask for registration fees, deposits or settlement before non-emergency admission, and a foreign insurer's card is not a universal guarantee of payment. International clinics are more likely to coordinate with insurers, but direct billing depends on the facility, policy and treatment. Call the assistance line before non-urgent care when possible, follow hospital instructions in a true emergency, and keep every Chinese-language invoice, receipt and medical record.
Evacuation deserves its own decision. A policy commonly pays to move you to the nearest facility equipped to treat the condition; it does not automatically pay for a flight to your preferred hospital in the United States. The insurer may also require advance authorization once you are stable. Save its emergency number offline, share the policy number with a traveling companion, and keep your passport, insurance details and medication list together.
Before paying, compare five clauses side by side: the emergency-medical maximum, the evacuation maximum, the deductible, the pre-existing-condition rule and the exact geographic coverage. Confirm that your dates include every travel day and that mainland China is not excluded. If your itinerary crosses into Hong Kong, Macau or another country, verify those legs separately rather than assuming one policy covers the whole route.
Visa paperwork is another common confusion. A standard United States tourist visa application does not come with a blanket rule requiring every traveler to buy insurance, but requirements can change and may differ by nationality, visa category and application location. Check the current China visa application service checklist for your own case. Never treat insurance as proof that entry will be granted; border officials still decide admission.
If something goes wrong, build a claim file immediately. Save six items: the policy number, passport details, diagnosis certificate, itemized bill, receipt and full medical record. Add a police or transport report when theft or an accident is involved. Notify the insurer promptly, ask whether a translation or original document is needed, and photograph every page before mailing anything. A complete file is far more useful than a persuasive story told weeks later.
The right China policy is therefore not the cheapest quote or the longest benefits menu. It is the one that covers your health history, dates, destinations and activities, with limits large enough for a serious hospital stay and an evacuation. Compare at least three policies before departure, then pair the decision with ChinaMira's arrival and visa-free transit guides so your insurance, entry paperwork and first day fit together.
Good to know
- Coverage screening targets
- For a 2026 trip, compare at least 3 policies with $100,000 emergency medical, $250,000 evacuation and a clearly stated per-person deductible.
- Policy dates
- Insure every travel day and add a 1–2 day buffer at each end if your policy permits; confirm mainland China is within the covered region.
- Claim document pack
- Keep 6 items: policy number, passport details, diagnosis certificate, itemized bill, payment receipt and medical record.
- Record retention
- Store paper and phone copies of the complete claim file for at least 12 months after return, since review and follow-up can continue after the trip.
- Emergency contacts
- Save 120 for ambulance, 110 for police and your insurer's 24-hour assistance number before arrival.
- Visa check, October 2026
- A standard US tourist visa application does not have a blanket insurance-purchase rule; verify the current checklist for your visa category and application center.
Frequently asked questions
Is travel insurance required to enter China in 2026?
Not universally for a standard United States tourist visa. Insurance requirements can vary by nationality, visa category and application center, so check the current China visa checklist for your case. Even when it is optional, emergency medical and evacuation coverage is still worth considering because treatment and medical transport can be expensive.
Does China travel insurance pay hospital bills directly?
Sometimes, but never assume it. Some international clinics and hospitals work with specific insurers, while others require payment or a deposit first. Call the policy's assistance line as soon as practical and ask whether direct billing and a payment guarantee are available. Keep all receipts and records if you must pay yourself and seek reimbursement.
What is not covered by travel insurance in China?
Common exclusions include routine care, elective procedures, unattended baggage, injuries caused by excessive alcohol, and activities not listed in the policy. Pre-existing conditions may also be excluded unless you qualify for a waiver. Read the exclusions and activity terms before buying, and buy an add-on if your itinerary includes trekking, diving or another higher-risk pursuit.
How much emergency medical coverage should I buy for China?
For a 2026 trip, compare policies with at least $100,000 in emergency medical coverage and $250,000 in medical evacuation coverage, then check deductibles and exclusions. Those figures are screening benchmarks, not a promise that every expense will be paid. Travelers with significant health risks may need higher limits or a specialist policy.
Does my US health insurance work in China?
Do not assume that it does. Many domestic health plans provide little or no coverage outside the United States, and Original Medicare generally does not cover care abroad. Check your plan's international benefits, network and reimbursement process before departure; if protection is limited, consider a separate travel-medical policy.
Keep exploring
Plan with ChinaMira
Turn this into a trip
Use this guide as a starting point — we can handle the route, guides, trains and the visa invitation letter.